Roof insurance claims in Surprise, documented the way adjusters want
A claim goes well when the damage is documented before anyone files, the adjuster sees the same photos you do, and the roof is built to the scope that gets approved. That's the whole job.
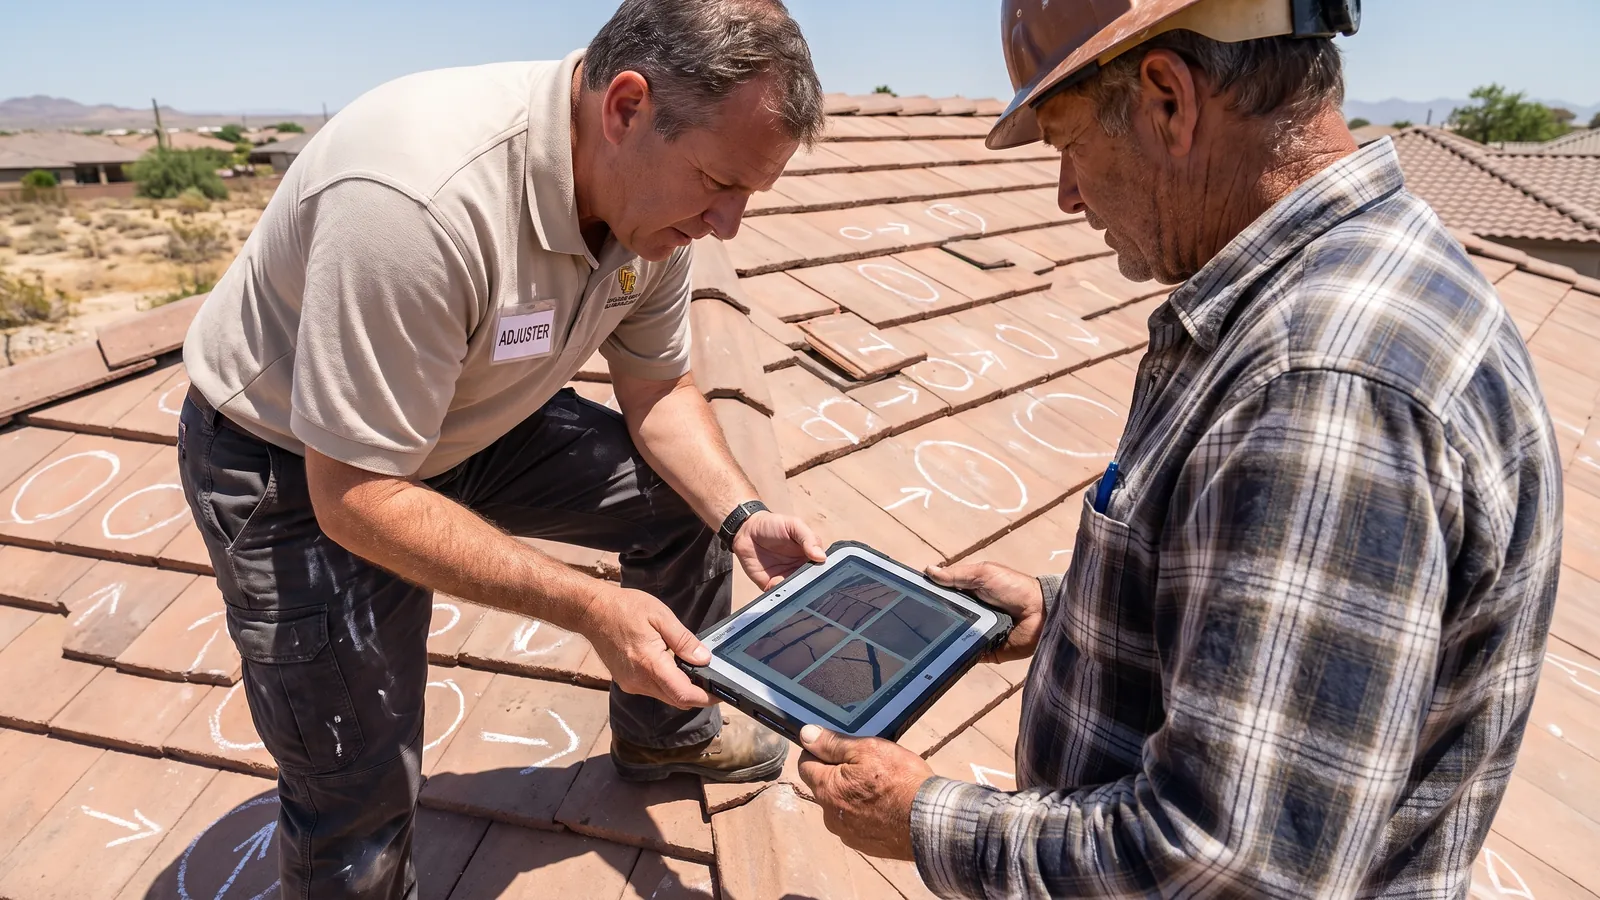
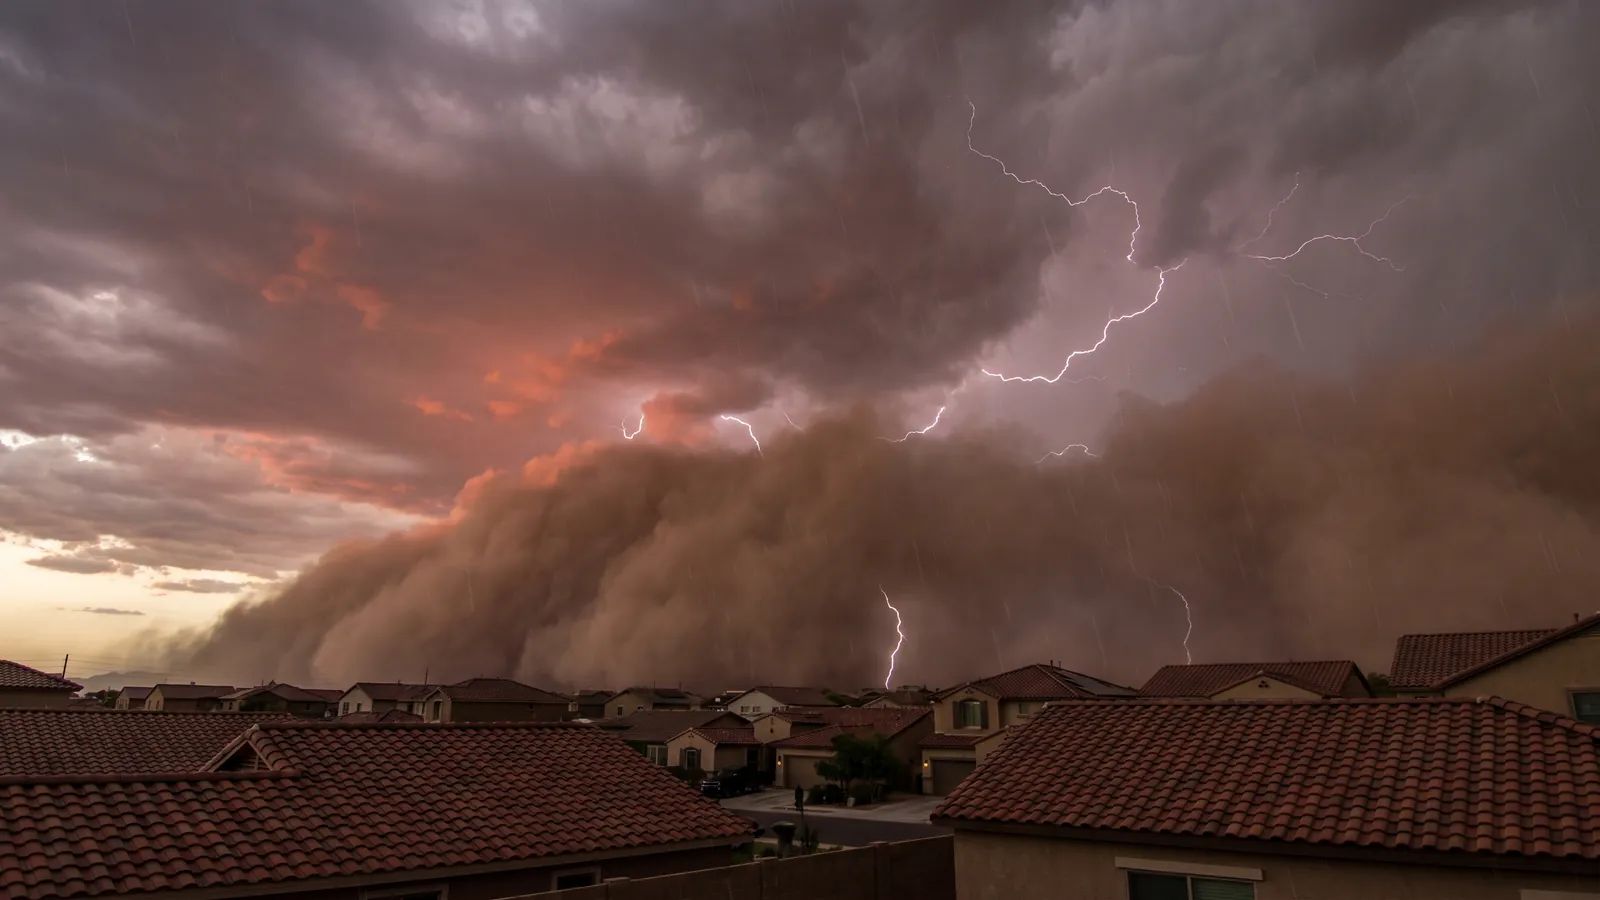
Arizona homeowner policies cover sudden storm damage — a microburst that lifts the ridge tiles, hail that cracks a slope, a limb through the deck — and don't cover wear, neglect or a roof that simply reached the end of its life. Most of the friction in a West Valley roof claim comes from the gray zone between those: a 2001 tile roof with felt that was already brittle, plus a storm that cracked thirty tiles and exposed that felt to the rain. The way through is documentation that separates the storm damage from the age, and that has to happen before the claim is filed, not after the adjuster has already written it up as 'wear and tear.'
So we inspect first: a tile-by-tile count of what's cracked and lifted, dated photos, the collateral damage on AC fins and screens that confirms hail, and a storm report tying it to a date. You file with your carrier — in Arizona only a licensed adjuster may negotiate your claim, and a roofer who offers to is breaking the law (A.R.S. 32-1158.02 and 20-321). When the adjuster comes, we're on the roof with them. If the claim is approved, we build to the approved scope, invoice your carrier's numbers, and you pay your deductible — and only your deductible. The same statute bars any contractor from paying, waiving or rebating it, caps the down payment at 50%, and gives you four business days to cancel for any reason and 72 hours to cancel if your claim is denied. Those protections are printed on our contract in ten-point bold, because the law says they have to be.
What's included
Documentation before you file
Tile counts, dated photos, collateral damage and a storm report for your address.
Adjuster walk-through
We meet your adjuster on the roof and walk the damage together so nothing gets written up as wear that was a storm.
Scope & supplements
A line-item estimate in the carrier's format, and properly documented supplements if the tear-off finds more.
Arizona matching rule
Arizona has no matching statute — the insurer owes the damaged portion only — so we document when a partial repair can't be matched and let the adjuster decide.
Built to the approved scope
Exactly the work your carrier approved, no padding, no 'free' upgrades.
Your deductible, your rights
Never waived or rebated; 4-business-day cancellation and 72-hour post-denial cancellation printed on the contract as A.R.S. 32-1158.02 requires.
Roof insurance claims cost in Surprise, AZ
| Job | Typical price | Notes |
|---|---|---|
| Storm inspection and documentation package | $0 | Photos, counts, storm report |
| Adjuster meeting | $0 | We're on the roof with them |
| Approved repair or replacement | Your deductible | Carrier pays the approved scope |
| Supplement documentation | $0 | When the tear-off finds hidden damage |
| Repair when the claim is denied | Quoted in writing | See repairs — we don't inflate it to 'make up' for the denial |
These are 2026 West Valley ranges so you can budget. Your written price is itemized — tile handling, underlayment, flashings, broken-tile allowance, permit when required, HOA paperwork — and good for 30 days.
Recent work
Questions we get about roof insurance claims
Should I file a claim for a few cracked tiles?
Usually not — a $400 repair under a $2,500 wind-and-hail deductible isn't a claim, and filing goes on your record. We'll tell you honestly whether what we found is worth filing before you call your carrier. When a storm has lifted a whole run of ridges or cracked thirty tiles on the west slope, it usually is.
How long does the insurer have to respond?
Arizona's claim-handling rules (A.A.C. R20-6-801) require the carrier to acknowledge your claim within 10 working days, complete the investigation within 30 days, and accept or deny within 15 working days of receiving your proof of loss. If you're stuck, the Department of Insurance's consumer line is (602) 364-2499.
Can you talk to my adjuster for me?
We can meet them on the roof, show them the damage and answer technical questions — that's what the walk-through is. We can't negotiate your claim or act as your adjuster; Arizona reserves that for licensed adjusters, and a roofer who does it is subject to ROC discipline.
What's the Residential Contractors' Recovery Fund?
An Arizona fund that can pay a homeowner up to $30,000 if a licensed contractor leaves a job unfinished or defective and can't make it right — one more reason the ROC license on your contract matters. Unlicensed roofers aren't covered.
My claim was denied. Now what?
You have 72 hours to cancel the repair contract under A.R.S. 32-1158.02, with any deposit refunded within 10 days. Then it's a plain repair conversation: we price the actual work at the actual cost, and you decide.